SysGroup lifts profit on fewer staff and looks to buy MSPs
SysGroup credits AI tools for a half-year in which costs fell as revenue rose. But leaving out an acquired business, its managed services revenue slipped as three larger customers cut back
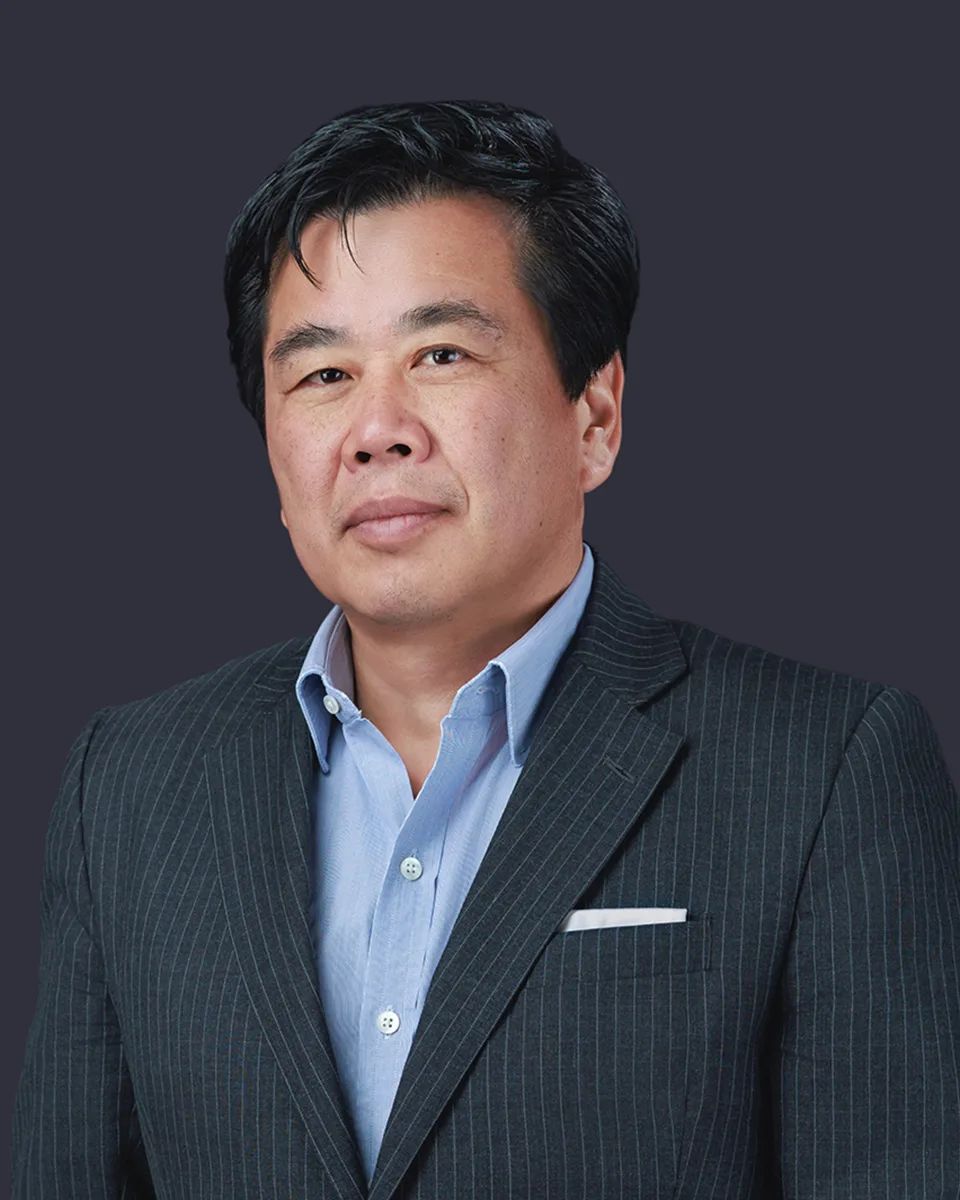
SysGroup, the AIM-listed managed service provider, reported on 18 November that revenue for the six months to 30 September rose 10.7% to £11.0m. Heejae Chae, executive chair, said the AI-enabled operating model the company calls MSP 3.0 had delivered “a structural improvement in profitability and cash generation”.
Adjusted EBITDA came to £1.0m, against £0.2m in the same half a year earlier, and a pre-tax loss turned into a small pre-tax profit.
The gain came from higher gross profit and a lower cost base. Adjusted operating expenses fell while revenue rose. Leaving out Saxis, the storage and data protection specialist bought in December 2025, the workforce went from 96 people to 75 in the year to September.
“That is the central claim of MSP 3.0 in practice: growth no longer depends on adding headcount,” the company wrote in the strategy statement published with the results. Chae had set that test in July. “We believe that the new cost base can support our growth ambition without significant increase in cost,” he wrote in his statement with the full-year results. The six months to September bore that out at group level.
Selling into Saxis
Chae said the results show MSP 3.0 “is beginning to answer the two big questions facing our industry: how do you grow without adding cost? and how do you cross-sell to the customers of an acquired business?” The strategy statement describes cross-selling into an acquired customer base as the point “where the revenue case for most MSP acquisitions is made and where it most often falls short”. Saxis, bought for £1.25m in cash, is the example SysGroup offers.
In its first full half-year with the group, Saxis contributed £1.1m of revenue, and almost half of that came from SysGroup products and services sold to Saxis customers. In July the company had put cross-sell at about 30% of the contracts Saxis had won since the deal.
SysGroup credits a system it calls the Client Intelligence Layer, which pulls data from the monitoring tools across a customer’s infrastructure, network, cloud applications and security into one profile. Account managers take that profile into customer meetings to show where security coverage is missing and which services would remove recurring tickets. “Our Client Intelligence Layer gives our teams evidence from each customer’s own environment, so every conversation starts from what the customer needs,” Chae said.
The company said integration had moved faster than with its previous acquisitions, helped by the same tools and customer data.
The managed services line
Managed IT services revenue, which includes professional services, grew once Saxis was counted. Without Saxis it was 1.0% lower, because three larger customers reduced the scope of their managed services contracts. Growth in professional services offset part of the fall.
Resale revenue nearly doubled, and SysGroup said the higher share of resale, mainly from Saxis, explains a slightly lower gross margin. Its organic growth measure adds back the SysGroup products sold to Saxis customers. Revenue outside Saxis was slightly lower than a year earlier, so the growth it reports as organic comes from those sales.
Chae said the model “is now helping us capture a larger share of the wallet from the customers we already serve”. The evidence SysGroup gives is a 28% rise in average annual contract values on the same period a year earlier. The statement does not name the customers that cut back or say whether more are expected.
SysGroup said partnerships with major cybersecurity vendors, building on its existing relationships with Zscaler and Rubrik, extend its reach alongside its direct sales team.
Room for more deals
Chae called growth without added cost and cross-sell “the keys to successful acquisitions” and said that “with a strong balance sheet in a fragmented market, we are well placed to make more of them”. SysGroup ended September with net cash of £3.6m, more than it held at the end of March, and Santander has approved a five-year extension of its revolving credit facility to April 2032. The company said it continues to pursue acquisitions in the UK MSP market. It booked no M&A costs in the half.
Saxis is small and mainly a resale business, and it is the only acquisition the statement gives cross-sell figures for. How the model performs at a larger provider with its own managed services contracts is untested in these figures.
The half-year settles one part of Chae’s case: costs fell while revenue rose, and SysGroup’s services sold into the Saxis customer base. Still open are whether its existing managed services contracts grow under the same model and whether the cross-sell repeats at the next acquisition. Chae presents the results to investors on 19 November.
Get The VETTDD BriefingThe week in B2B technology, every week.
Subscribe freeSources
- SysGroup, “Half-year Results to 30 September 2026”, RNS announcement, 18 November 2026. https://otp.tools.investis.com/clients/uk/sysgroup_plc/rns/regulatory-story.aspx?cid=814&newsid=2123460
- SysGroup, “Final Results for the year ended 31 March 2026”, RNS announcement, 8 July 2026. https://otp.tools.investis.com/clients/uk/sysgroup_plc/rns/regulatory-story.aspx?cid=814&newsid=2073896
- SysGroup, “Notice of Results, Investor Presentation and Mello”, RNS announcement, 28 October 2026. https://otp.tools.investis.com/clients/uk/sysgroup_plc/rns/regulatory-story.aspx?cid=814&newsid=2116790
Editor
The VETTDD editorial desk. Interviews, analysis, columns and news briefs on the decisions shaping B2B technology.
More from Editor
The week in B2B technology, in five minutes
Every week: the interview, the briefs that matter and one view from the editor. Free.